Nvidia stock has hit a wall slightly below its all-time high despite the optimism of the artificial intelligence spending, its cheap valuation, and the mega $150 billion buyback plan. NVDA was trading at $229 on Tuesday, down modestly from the year-to-date high of $236.
Nvidia to benefit from AI spending plan
NVDA stock is stuck below the all-time high despite the ongoing AI data center buildup. Analysts believe that this buildup will continue, with Bain predicting that spending will jump to $6 trillion in the next few years. A PwC report showed that AI spending will jump to $32 trillion by 2032.
Nvidia is set to benefit from this growth because of its market share in the industry, where its Blackwell chips are used widely by top companies like Microsoft and Amazon.
As a result, its revenue growth is set to keep rising in the coming years. The average estimate among analysts is that its annual revenue will jump by 90% this year to $411 billion. In its recent report, the company said that its annual revenue will rise by 70% next year.
If this trend continues, the real figure will likely be much higher, since Nvidia tends to be highly conservative in its guidance. For example, management excluded its China business from its forecasts. That could change now that China is reportedly considering allowing purchases of Nvidia’s advanced chips by top companies like ByteDance and Alibaba.
Nvidia is highly undervalued, justifying its buyback plan
Meanwhile, there are signs that the company is highly undervalued, with the forward price-to-earnings ratio of 24, much lower than the five-year average of 42. Its rule-of-40 multiple is also highly encouraging.
The company’s forward PEG ratio of 0.47 is much lower than the sector median of 1.25. This valuation explains why the company announced a plan to repurchase shares worth $150 billion this week. In total, the management plans to repurchase shares worth over $235 billion.
Share repurchases are usually bullish because they reduce the number of outstanding shares, boosting its earnings-per-share. It also means that investors will be receiving more dividends.
Potential risks remain
Nvidia’s underperformance is mostly because of the rising risks. The most notable one is that there is fear of the ongoing artificial intelligence bubble.
Further, its biggest customers are launching their own chips, which may affect its demand and margins over time. OpenAI has unveiled Jalapeno, while Google’s TPU is gaining market share in the computing industry. Amazon and Microsoft’s chips are also doing well.
The company is facing the circular investing risk. This is where it is investing in its customers, who then use the resources to acquire its chips. Most recently, it has organized funding from some of the biggest companies in the United States, like Goldman Sachs and Brookfield.
Nvidia stock price technical analysis
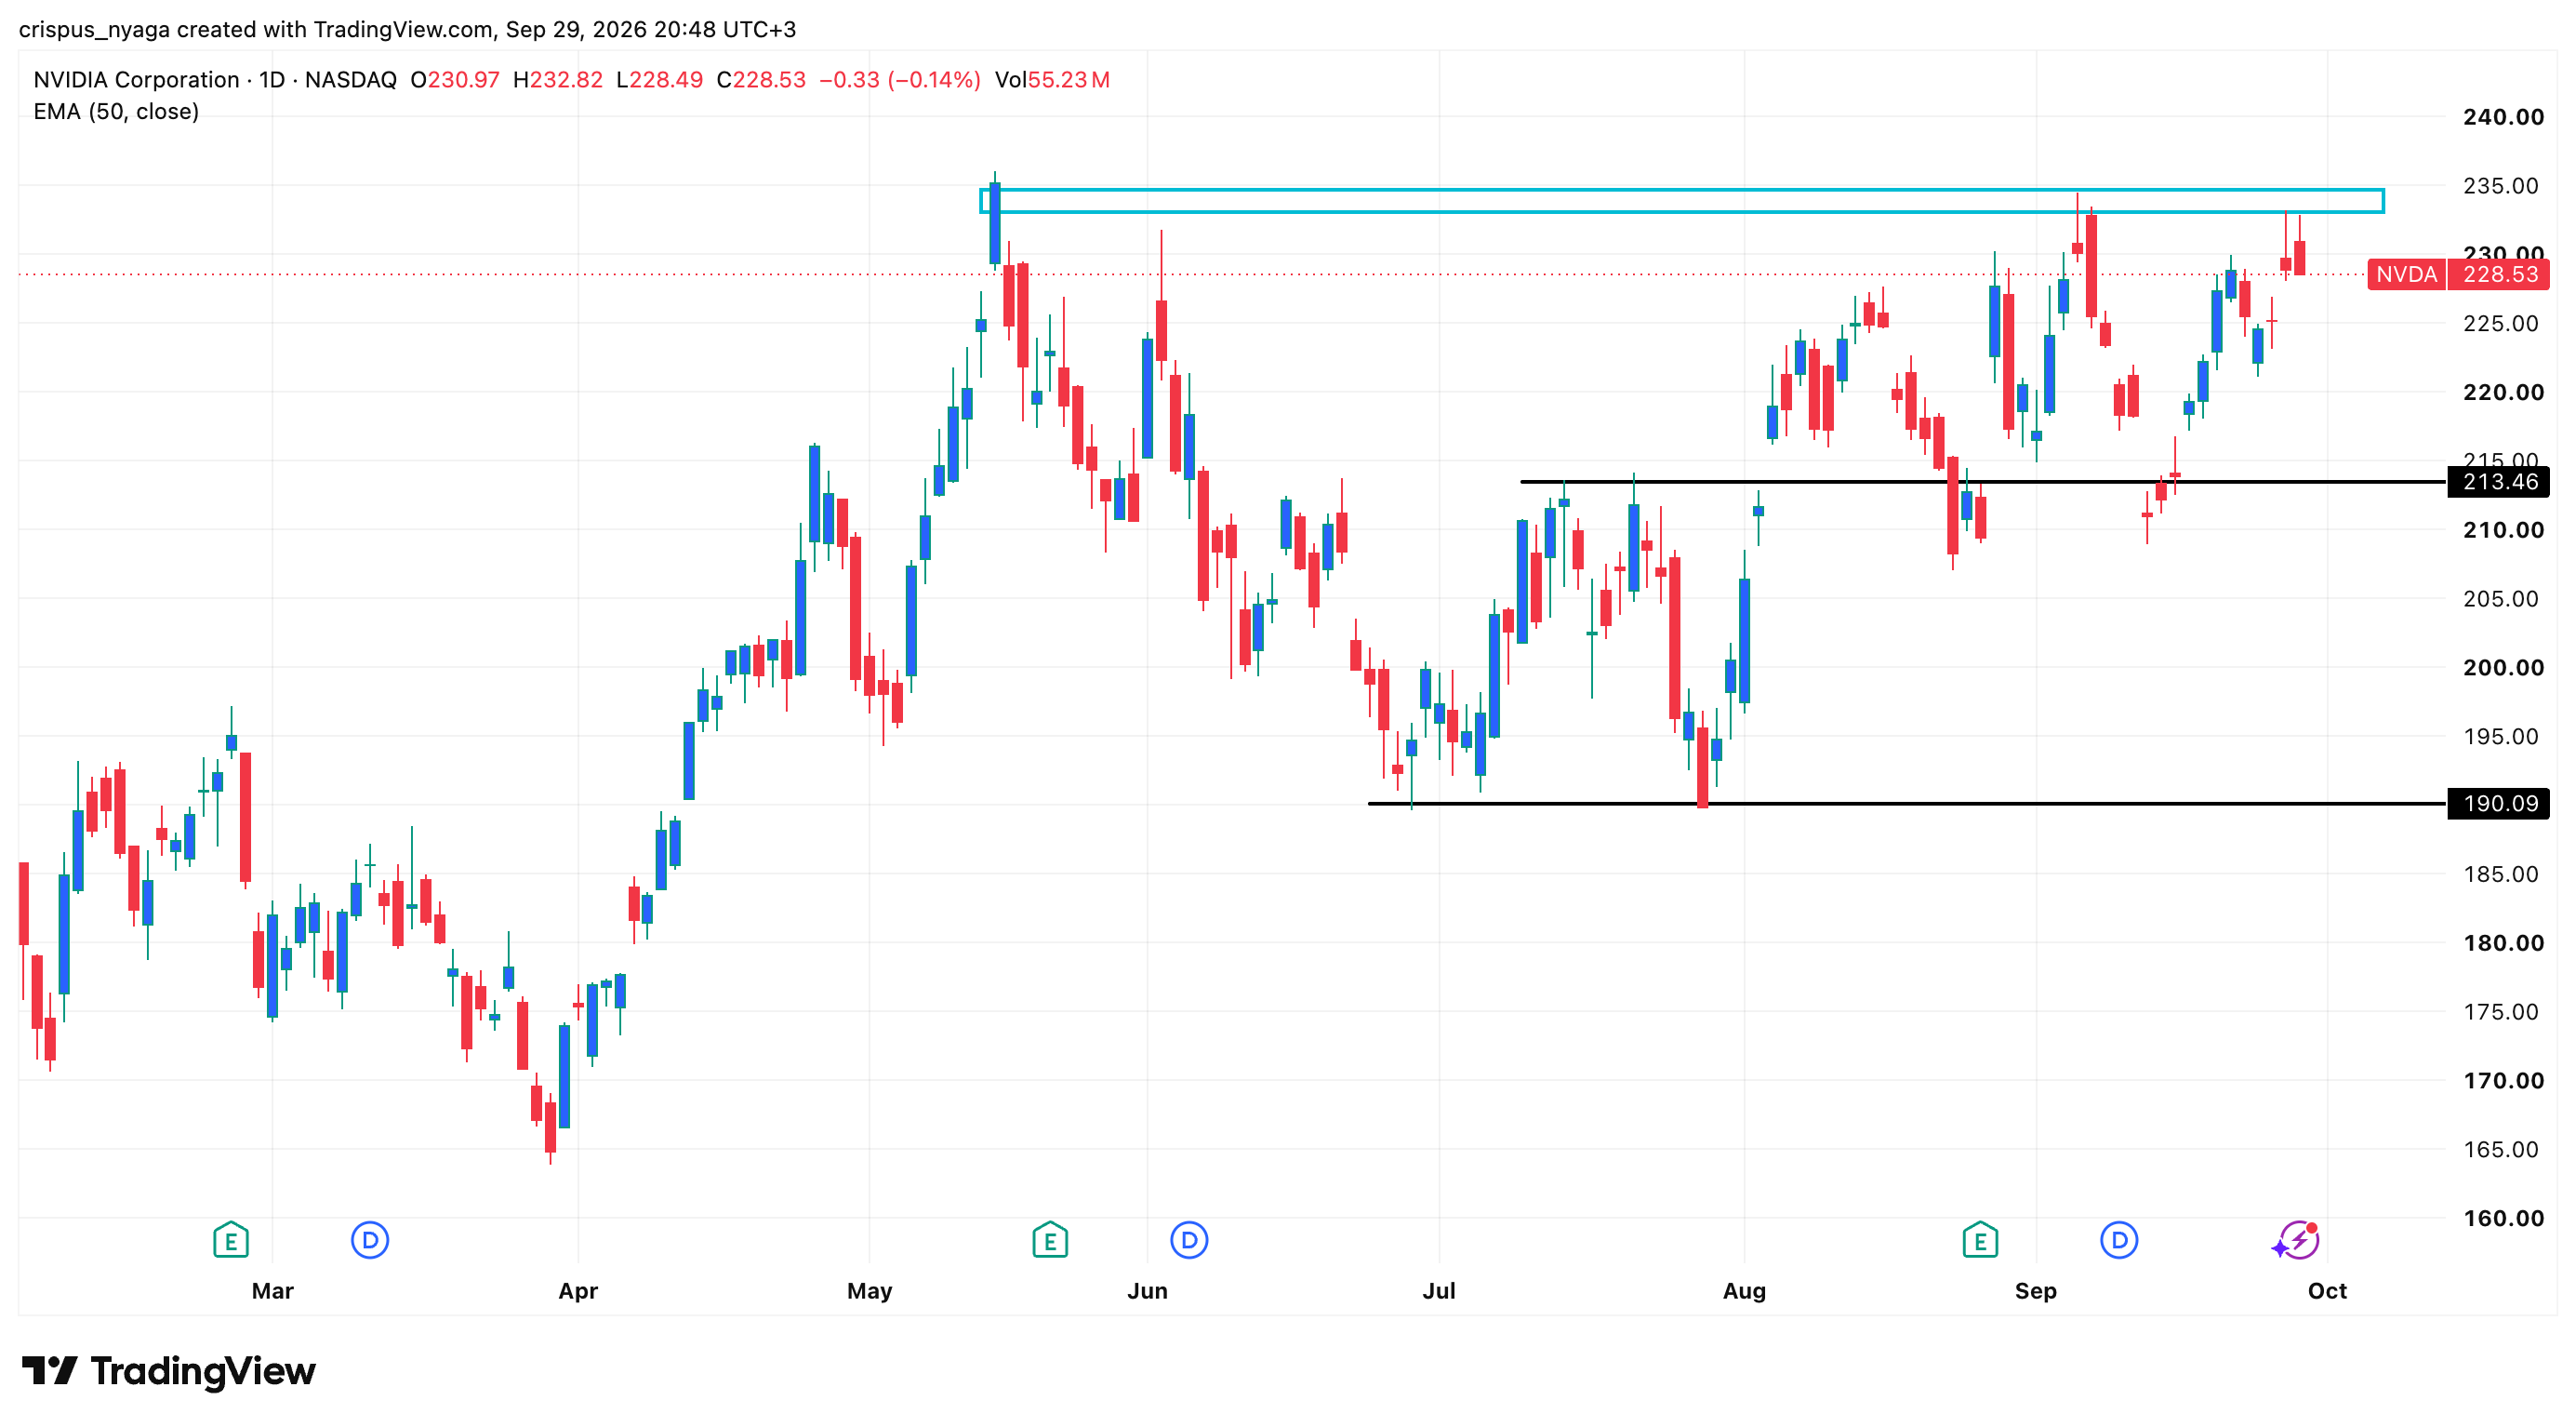
NVDA stock chart | Source: TradingView
The daily chart shows that NVDA formed a double-bottom pattern at $190 and a neckline at $213, its highest level on July 15 this year. This pattern normally leads to more gains over time.
The stock remains above the 50-day and 100-day Exponential Moving Averages (EMA), which is a highly bullish aspect.
The risk, however, is that it has formed a diamond reversal pattern, which normally leads to a bearish reversal. It has also found substantial resistance near its all-time high.
Therefore, what happens next will be important. A rebound above the resistance level of $236 will confirm the bullish breakout and point to more gains, potentially to $250 and above. On the other hand, a drop below the support of $213 will invalidate the bullish outlook.
The post Nvidia stock sends mixed signals as tailwinds meet headwinds appeared first on Invezz